When a drone came down beside a building in Dubai Creek Harbour on 12 March, the fire was small and nobody was hurt. The question it left behind is larger: had the damage been to your car, your flat or to you, which of your insurance policies would have paid? For war damage in the UAE, the standard policies mostly say no, with one important exception in health cover. This is what each type of policy does, the add-ons that now exist, and what they cost.
The short answer
Standard UAE insurance policies typically exclude war, Khaleej Times reported in April 2026, and the cover is sold instead as add-ons. That holds for car and home insurance, and travel policies list war, military activity and airspace closures among their usual exclusions.
The exception is emergency medical care in Dubai: a directive in force since October 2025 requires health insurers to cover emergencies until the patient is stabilised, whatever the cause. After that, your policy wording decides.
War add-ons now exist for cars, from around AED 90 at Sukoon, and Orient sells political violence cover for homes and vehicles. None of them pays for damage that happened before you bought it.
Why this is a real question in 2026
Since the start of March 2026 the UAE has faced Iranian missile and drone attacks, with its air defences intercepting them as they come in. On 12 March alone, Dubai Media Office reported a minor fire in a Dubai Creek Harbour building after a drone fell nearby, debris from an interception hitting a building facade on Sheikh Zayed Road, and a drone crash in Al Bada’a. Nobody was hurt in any of the three.
The UK Foreign Office page on the UAE, last updated on 24 July 2026, describes Iranian strikes and retaliation in the region since 8 July, a risk of escalation and possible airspace closures. It does not advise against travel. For most residents the risk is practical rather than dramatic: a car under falling debris, a cracked window, a flight home that does not leave. Those are the losses people buy insurance for, and they are where the war exclusions sit.
The clause that decides it
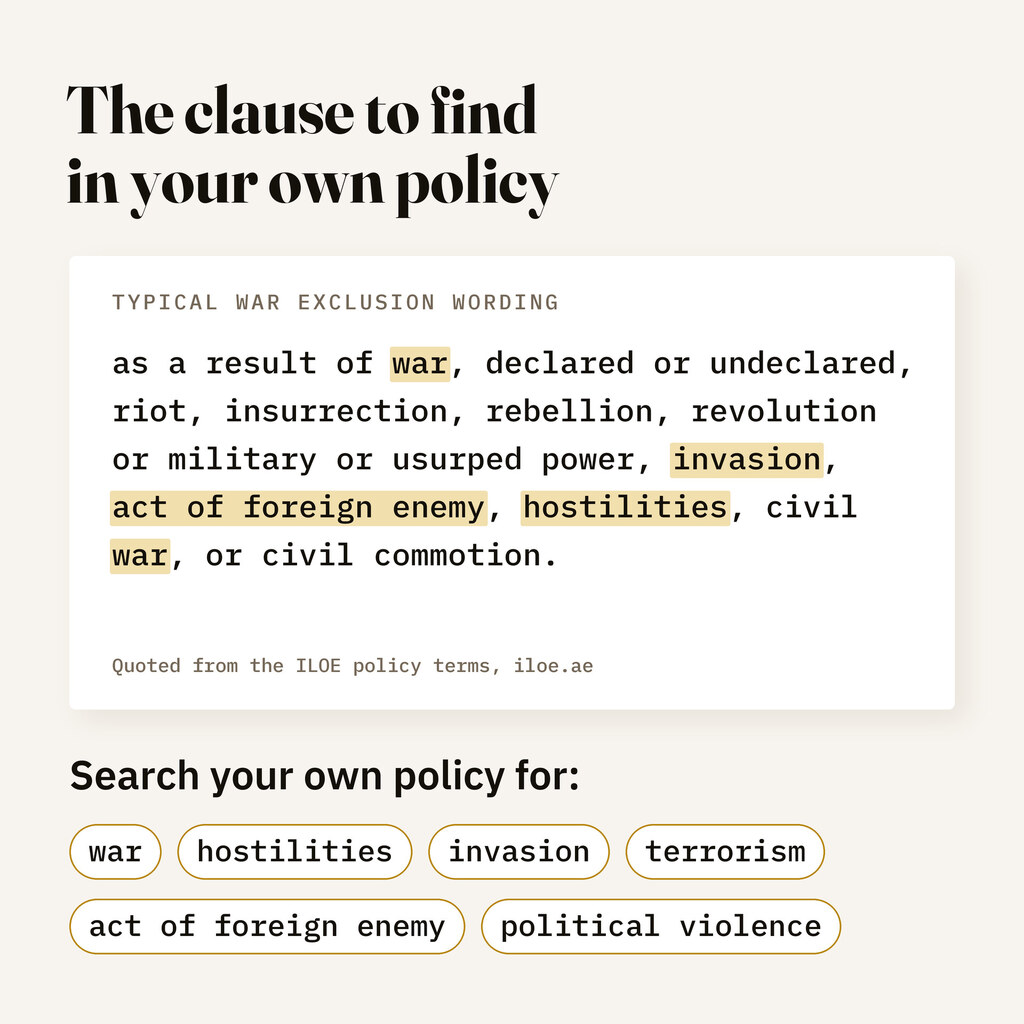
Look for the section headed general exclusions: that is where war sits. Khaleej Times put it plainly in April 2026, writing that standard insurance policies in the UAE typically exclude war-related risks, which are instead covered through add-on benefits. The wording varies from one insurer to the next. The ILOE scheme’s version, shown above, lists war declared or undeclared, invasion, act of foreign enemy, hostilities, civil war and civil commotion.
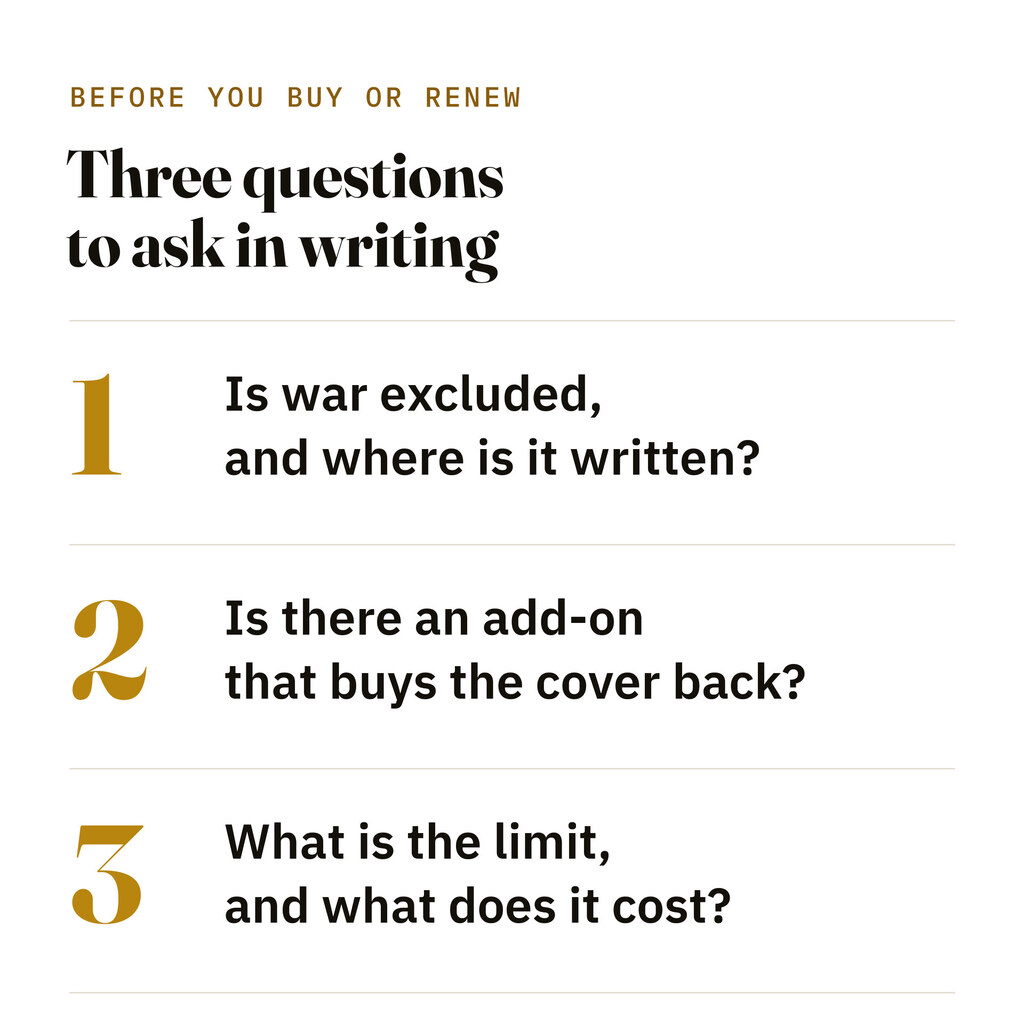
Two points follow. The definition is what matters: Ibrahim Karam, chief executive of R2S Insurance Brokers, told The National that exclusions may apply for war-related risks depending on how they are defined. And whether debris from a successful interception counts as war damage is a question of wording, on which we could find no common published position among UAE insurers. Read the clause before you need it, and get the answer in writing.
Policy by policy: what pays
This is the position we could document on 11 September 2026. Each row is explained further down.
| Policy | Standard cover | What changes it |
|---|---|---|
| Car, comprehensive | Excluded | A war add-on bought before the damage, from Sukoon, GIG Gulf or Orient |
| Home and contents | Usually excluded | Orient’s political violence cover for residential units |
| Health, in Dubai | Emergency care | Covered until you are stable, whatever the cause. After that, your wording decides |
| Travel | Usually excluded | Conflict cover in some products, such as Emirates’ Comprehensive Travel Cover |
| Job loss, ILOE | Excluded | Nothing: loss of work based on the state’s declaration of war is excluded |
| Life | Check wording | We found no published market-wide position |
Car: the add-ons, and what they cost
A comprehensive motor policy does not pay for war damage. GIG Gulf points to General Exclusion 10 of the UAE’s unified motor policy, which lists war, invasion, hostilities and civil unrest, and The National reported in May 2026 that war, terrorism and warlike operations remain standard exclusions. At least three insurers now sell a way to buy that cover back.
| Insurer | Who can buy it | Limit | Price |
|---|---|---|---|
| Sukoon | Comprehensive motor customers only | The car’s insured value, up to AED 5 million | From around AED 90, priced pro rata on value and the time left on the policy |
| GIG Gulf | Private saloons, sedans, SUVs and 4WDs on Motor Prestige, Motor Perfect Plus or Motor Perfect | Full vehicle value, AED 100,000 or AED 50,000 | 0.5% additional premium, active 48 hours after purchase |
| Orient | Vehicle owners | Not published | Not published |
Two details matter more than the price. GIG’s cover starts 48 hours after you buy it, so it cannot be added once something has happened. And Sukoon sells its add-on only to comprehensive customers, so a driver with third-party cover has nothing to attach it to.
Home: why almost nobody is covered
Most household insurance contracts contain war exclusions, The National noted in April 2026. The product that buys them back, political violence insurance, has mainly been bought by businesses. Sanjay Bhagwan Babur, chief executive of Cosmos Insurance Brokers, quoted minimum premiums of about $30,000 and rates of 2.5% to 5% depending on location, against 0.1% to 0.2% before the conflict. Those policies cover fixed assets such as buildings and warehouses, not cars.
For individuals, the change came on 14 May 2026, when Orient Insurance launched Political Violence, including War, for Residential Units for homeowners, alongside a version for personal vehicles. No prices were published with the launch.
If you rent, the building is your landlord’s to insure. Your belongings are yours, and a standard contents policy is likely to carry the usual war exclusion, so ask whether any political violence option covers a tenant’s contents before assuming it does.
For some UAE nationals, yes. Cabinet Resolution No. 135 of 2026 allows up to AED 350,000 for damage to a home and essential household items, for national families receiving federal or local social support, on the basis of an official damage report, Khaleej Times reported in August 2026.
For expatriate residents we found no equivalent scheme as of 11 September 2026. The relief measures Gulf News listed in May, including loan deferrals, rent-free periods offered by major landlords and a three-month deferral of some government fees, deal with cash flow, not damage.
Health: emergency care is covered, the rest depends
This is the one place where Dubai’s rules override the exclusions. The Dubai Health Insurance Corporation’s emergency coverage directive, effective 27 October 2025, requires health insurance policies to cover all emergency conditions up to stabilisation, irrespective of the underlying cause, including causes excluded under standard policy terms. If no other insurance applies, the health insurer bears the cost up to that point.
The same directive requires insurers to cover emergencies regardless of network, and not to reject or delay those claims over network, location or pre-authorisation. What it does not do is extend the obligation past stabilisation. Follow-up surgery, rehabilitation or a longer hospital stay fall back on your own policy, war exclusion included.
This is a Dubai rule, and other emirates apply their own. If your policy was issued elsewhere, check which regulator it answers to. Our guide to health insurance costs explains how Dubai policies are tiered and priced.
Travel: the foreseeability trap, and one exception
War, military activity and airspace closures are typically listed under travel policy exclusions, comparison platforms told Gulf News in March 2026. Timing matters just as much. A policy bought before a conflict escalated, or before a travel advisory was issued, may keep some protection. A trip booked once the situation was widely known can be classed as foreseeable, which limits cover. Ordinary medical emergencies abroad stay covered, as long as the illness or injury was not caused by the conflict.
The exception is Emirates. Its Comprehensive Travel Cover, launched on 17 June 2026 with Travel Guard, adds conflict cover that reimburses medical expenses up to US$25,000 and a free trip extension of up to 30 days, and Emirates states that the cover is not restricted by government travel advice. It is sold on emirates.com at booking or through Manage Booking, in markets that include the UAE and the UK. The hotel stays during disruption are an airline service, not insurance, and terms vary by market.
Whatever you buy, check one line: whether the cover depends on your government’s travel advice for the destination. Our travel insurance guide covers the other exclusions that catch people out.
Job loss: ILOE carries its own exclusion
The UAE’s compulsory job loss scheme has a war clause too. Its policy terms make a claim ineligible when the loss of work is based on the state’s declaration of war, declared or undeclared, hostilities, invasion, civil war or civil commotion, among other events.
An ordinary redundancy, decided by an employer for business reasons in a difficult year, is assessed on the usual conditions: 12 months of cover, no resignation, a claim within 30 days. The policy terms do not say how a claim is treated when the two overlap, and we found no published guidance. Our ILOE guide walks through the claim itself.
If something is damaged: the first days
None of this changes what to do in the moment. Once everyone is safe, the paperwork below is what any claim, refusal or support application will turn on.
- Photograph everything before it is movedWide shots and close-ups, with the date on your phone, including the street or car park and anything that shows the cause.
- Get the official reportAsk the police or civil defence at the scene which document they issue. The federal scheme for nationals will not pay without an official damage report, and it is the first thing an insurer is likely to ask for.
- Tell your insurer in writing, even if you expect a noQuote your policy number, and ask for any refusal in writing with the exclusion clause it relies on.
- If you rent, write to your landlord the same dayThe building is theirs to insure and repair, and a dated message protects you when the deposit comes up.
- Keep every receiptTowing, a hotel night, replaced glass. If cover exists anywhere, it will be claimed against receipts.
Questions we get asked
- Does car insurance cover drone or missile debris damage in the UAE?
- Not under a standard comprehensive policy, which excludes war, terrorism and warlike operations. Cover comes only from a war add-on bought before the damage, such as those sold by Sukoon, GIG Gulf and Orient. Whether debris from an interception counts depends on the wording, so ask your insurer in writing.
- Is there home insurance that covers war damage in Dubai?
- Yes, but it is new and specific. Orient Insurance launched Political Violence, including War, for Residential Units in May 2026, without published prices. Most standard household contracts exclude war.
- Will my health insurance pay if I am injured in an attack?
- In Dubai, emergency treatment must be covered until you are stabilised, whatever caused the injury, under the Dubai Health Insurance Corporation directive effective 27 October 2025. Treatment after stabilisation depends on your policy wording.
- Does travel insurance cover a trip to the UAE during the conflict?
- Usually not for losses caused by the conflict. War, military activity and airspace closures are typical exclusions, and trips booked once the situation was widely known can be treated as foreseeable. Emirates sells a Comprehensive Travel Cover with conflict medical cover up to US$25,000.
- Can I claim ILOE if I lose my job because of the war?
- Not if the loss of work is based on the state’s declaration of war or similar events, which the ILOE policy terms exclude. An ordinary redundancy is assessed under the usual conditions.
- Does the UAE government compensate residents for war damage?
- Cabinet Resolution No. 135 of 2026 provides up to AED 350,000 for home damage to UAE national families receiving social support. We found no equivalent scheme for expatriate residents as of 11 September 2026.
- UK Foreign, Commonwealth and Development Office, UAE travel advice updated 24 July 2026, read 11 September 2026
- Gulf News for the 12 March incidents in Dubai, citing Dubai Media Office
- Khaleej Times for standard exclusions and add-ons, 20 April 2026
- The National for household exclusions and political violence pricing, 9 April 2026
- The National for the Sukoon motor war add-on, 15 May 2026
- GIG Gulf for General Exclusion 10 and its War Cover terms, read 11 September 2026
- Gulf News for the four Orient war risk products, 14 May 2026
- Al-Futtaim, Orient Insurance announcement May 2026
- Dubai Health Insurance Corporation, Emergency Coverage Policy Directive effective 27 October 2025, sections 4.1 and 4.6.3
- Gulf News for travel exclusions and foreseeability, 12 March 2026
- Emirates media centre for Comprehensive Travel Cover, 17 June 2026
- ILOE policy terms and conditions for the war exclusion in the job loss scheme
- Khaleej Times for Cabinet Resolution No. 135 of 2026, August 2026
- Gulf News for the relief measures since March 2026, updated 12 May 2026
Found a clause in your policy you cannot make sense of? Ask us what to put to your insurer.
Ask us your question